WALL STREET LOSES TRILLIONS: IS THE ERA OF AI INVESTMENT EUPHORIA COMING TO AN END?
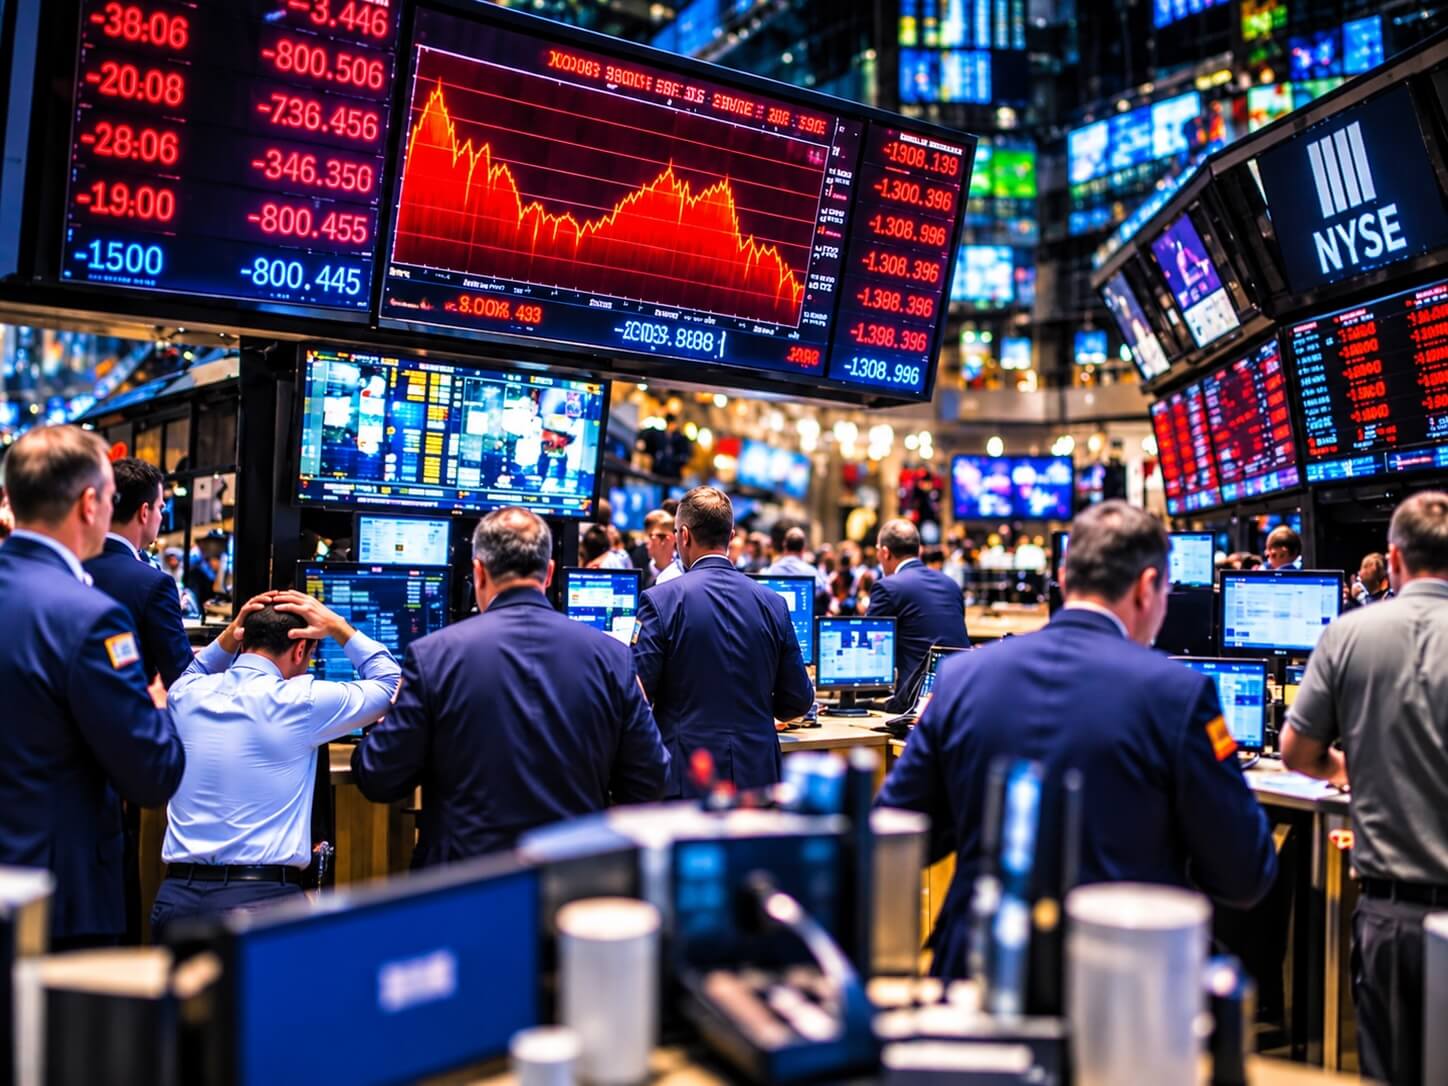
The U.S. stock market is undergoing a significant reassessment of the technology sector. After several years of explosive growth in enthusiasm for artificial intelligence, investors are increasingly asking whether the world’s largest technology corporations can justify their multibillion-dollar investments and record-breaking market valuations.
According to Gulf Business, Wall Street has lost approximately $3 trillion in market capitalization amid a sell-off in stocks associated with artificial intelligence. Although the scale of these losses requires independent verification, the developments have once again brought attention to one of the most pressing questions facing the global economy: has the investment boom surrounding artificial intelligence evolved into another financial bubble?
Over the past several years, artificial intelligence has become more than just a technological trend. It has emerged as one of the primary drivers of growth in the U.S. stock market. Investors have poured enormous amounts of capital into companies developing semiconductors, cloud computing, software, and the infrastructure required to train artificial intelligence models. NVIDIA, Microsoft, Alphabet, Amazon, and Meta have found themselves at the center of this technological race, while expectations of future AI-driven revenues have become a major justification for the rising value of their shares.
However, financial markets cannot thrive on expectations of technological progress alone. Sooner or later, investors begin demanding tangible results: revenue growth, sustainable profitability, and returns on invested capital. This is where the central contradiction of the current technology boom becomes apparent. Companies are investing tens of billions of dollars in building data centers, purchasing specialized processors, expanding energy infrastructure, and training increasingly sophisticated artificial intelligence models. Yet the timelines for recovering these investments remain uncertain, while the commercial potential of many emerging products has yet to be fully demonstrated.
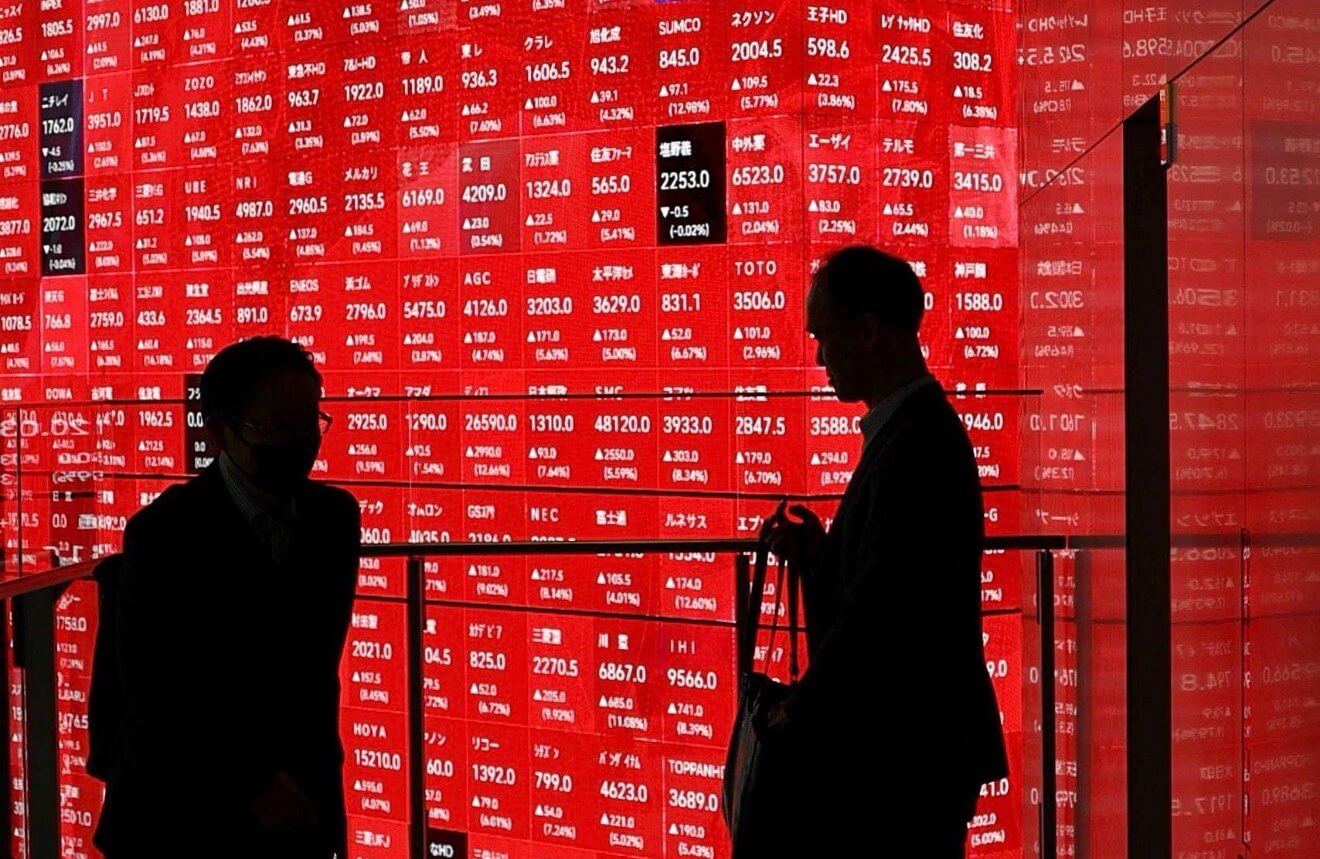
This situation is particularly sensitive for companies whose market valuations already reflect expectations of extraordinary growth for years to come. Even a modest deterioration in financial forecasts can trigger a sharp decline in share prices. Investors begin reassessing business valuations, taking profits, and reducing their exposure to the most expensive technology assets. Such developments do not necessarily indicate a crisis in the technology itself, but they may signal the end of a period in which virtually any company associated with artificial intelligence automatically attracted heightened investor interest.
Financial history offers several examples of similar developments. In the late 1990s, the rapid expansion of the internet triggered a massive investment boom accompanied by soaring valuations of technology companies. Many investors believed that the emerging digital economy had permanently rewritten the traditional rules of business valuation. The internet did indeed transform the global economy, but that transformation did not prevent the collapse of numerous overvalued companies when the dot-com bubble began to burst in 2000.
Today, comparisons with that period are becoming increasingly relevant. Artificial intelligence undoubtedly has the potential to fundamentally reshape the global economy. However, the existence of a revolutionary technology does not automatically guarantee profitability for every company investing in it. Moreover, technological revolutions are often accompanied by periods of excessive optimism, during which asset prices rise significantly faster than the underlying financial performance of businesses.
Nevertheless, there is an important distinction between the current situation and the dot-com era.
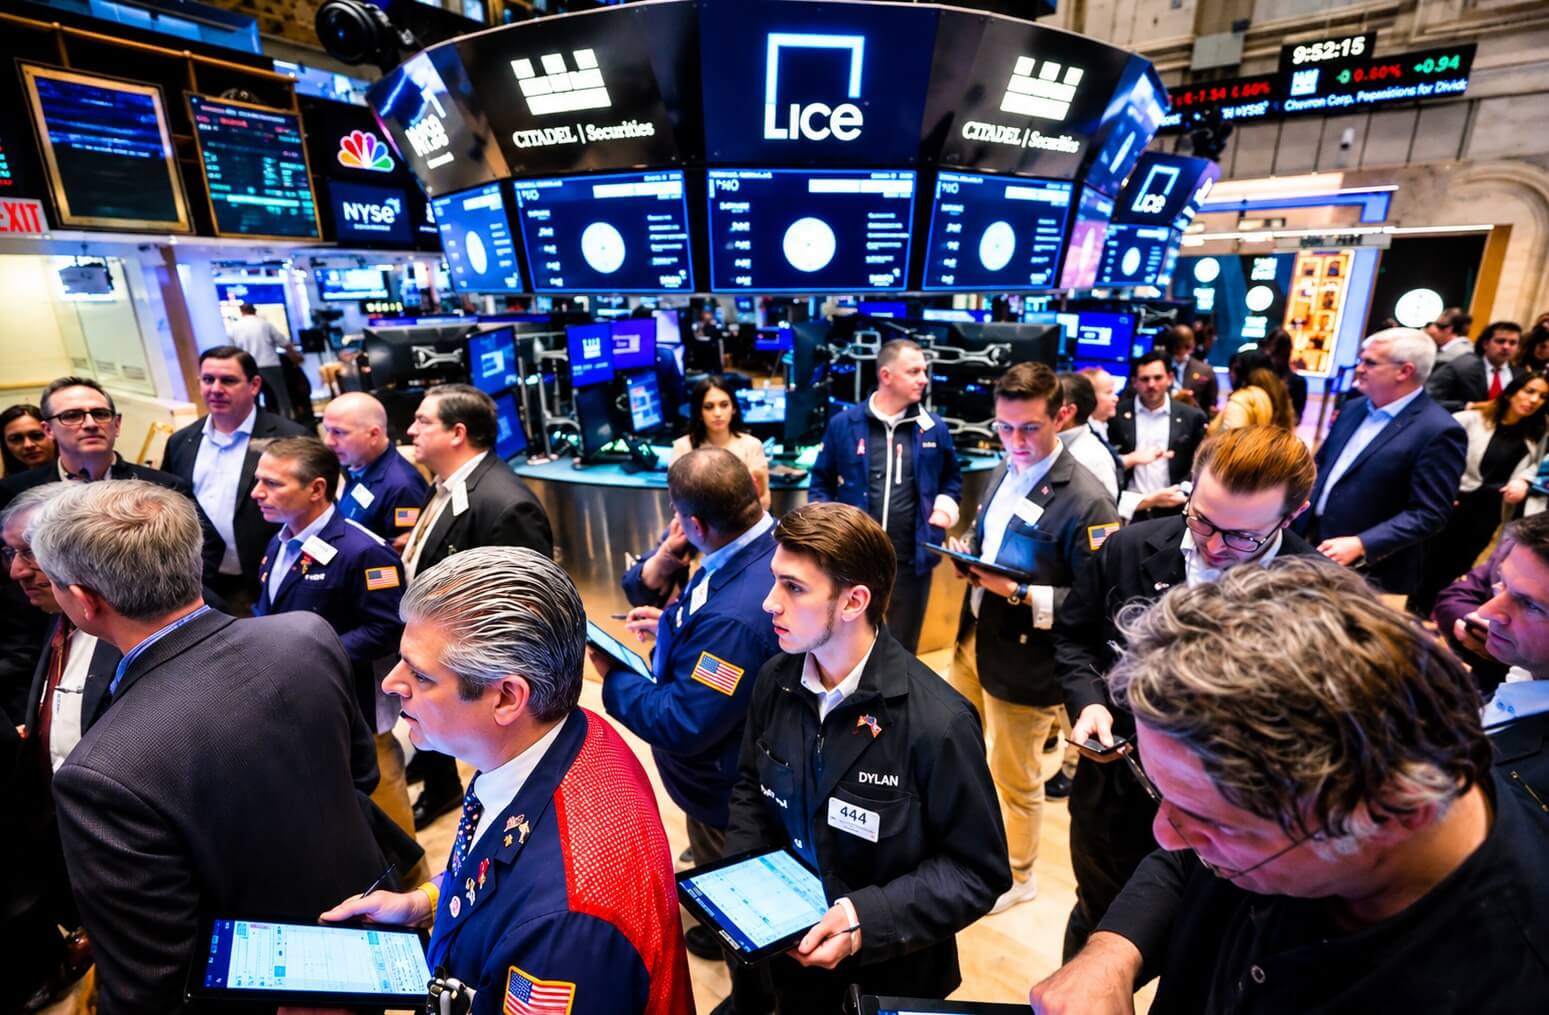
Many of today’s technology leaders are highly profitable corporations with strong cash flows, global customer bases, and diversified revenue streams. Microsoft, Alphabet, Amazon, and Meta operate established business models capable of financing large-scale investments in artificial intelligence. Consequently, a potential correction in their share prices does not necessarily represent a threat to the companies’ long-term survival.
Particular attention is focused on NVIDIA, which has become one of the defining symbols of the artificial intelligence revolution. Demand for its high-performance processors has surged alongside the rapid expansion of AI computing infrastructure. However, the company’s future performance depends not only on its technological leadership but also on the willingness of its largest customers to continue increasing capital expenditure. If the pace of data center construction slows or major corporations adopt a more cautious approach to investment, expectations for future revenues across the entire industry could be affected.
The broader macroeconomic environment in the United States also plays a critical role. Interest rates, inflation, borrowing costs, and economic growth prospects directly influence technology company valuations. The higher the cost of capital, the more cautious investors become toward businesses whose expected profits lie far into the future. Under such conditions, even strong financial results may not be sufficient to sustain previous rates of share price appreciation.
At the same time, reports of trillions of dollars in lost market capitalization require careful interpretation. A $3 trillion decline in the combined market value of stocks does not mean that investors have literally withdrawn an equivalent amount of cash from the stock market. Market capitalization is calculated based on prevailing share prices, and its decline reflects changes in how market participants value companies. Nevertheless, such a reassessment can have very real consequences for investment funds, retirement savings, and international financial markets.
The influence of the American technology sector has long extended far beyond Silicon Valley. The world’s largest technology corporations account for a substantial share of major U.S. stock indices, while their shares are held in the portfolios of institutional and individual investors around the world. As a result, a sharp decline in the valuations of just a handful of companies can trigger a chain reaction affecting multiple asset classes and international capital markets.
At the same time, it would be premature to declare the end of the artificial intelligence era. The technology continues to penetrate financial services, healthcare, manufacturing, logistics, education, and the media industry. Companies are increasingly using AI-powered systems to automate processes, analyze data, develop new products, and improve productivity. However, as the industry matures, investors are likely to focus less on the scale of technological ambitions and more on the ability of businesses to convert innovation into measurable financial results.
This transition from investment euphoria to financial discipline may ultimately become the defining characteristic of the next phase of artificial intelligence development. The winners will not necessarily be the companies making the loudest claims about their technological achievements, but rather those capable of generating sustainable demand, controlling costs, and demonstrating the economic efficiency of their solutions.
For investors, the current situation serves as a reminder of one of the fundamental principles of financial markets: even the most promising technology can become a poor investment if its valuation already reflects excessively optimistic expectations.
Artificial intelligence may indeed become one of the most important economic revolutions of the 21st century. But Wall Street’s history demonstrates that revolutionary technologies and endlessly rising stock prices are far from the same thing.
The central question is no longer whether artificial intelligence will change the world, but how much investors are willing to pay for that future — and which companies will ultimately succeed in turning it into sustainable profits.